Licensed Florida real estate brokerage
Moving to Florida in Oakland Park, FL
Moving to Florida in Oakland Park and the surrounding area, with a licensed real-estate professional. No obligation.
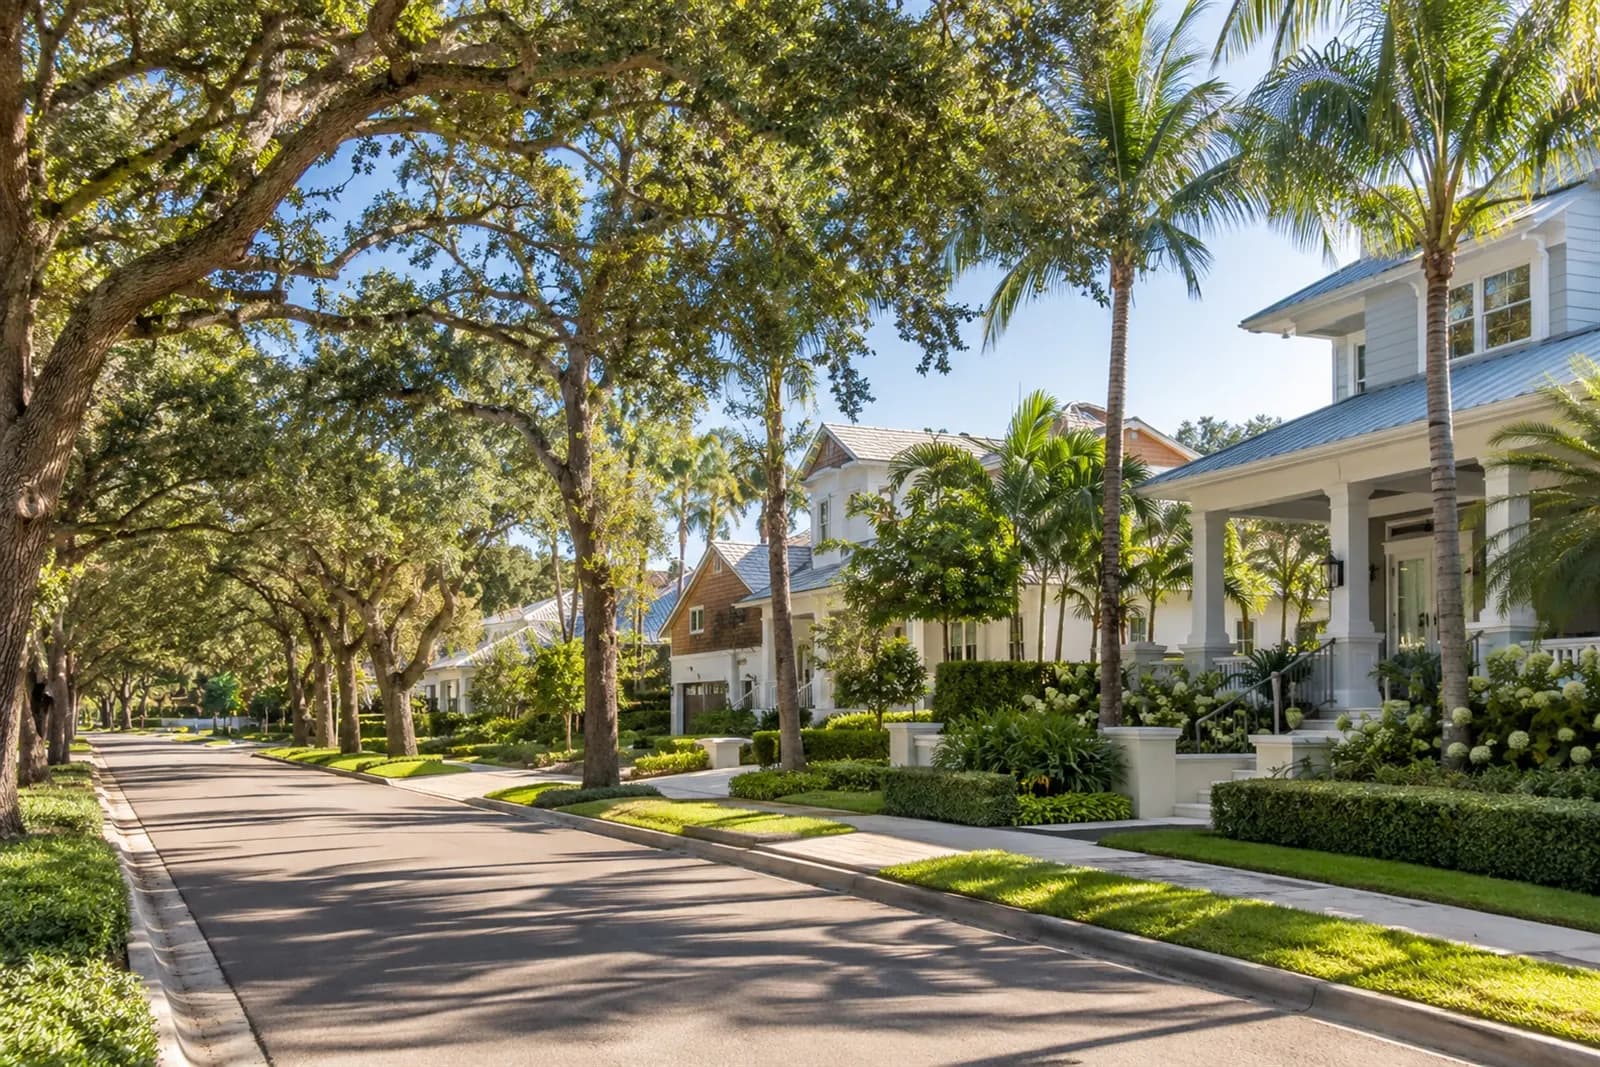
Oakland Park is a city of roughly 44,105 people a few miles west of the Atlantic, threaded by the tidal Middle River and its canals. That location shapes almost every part of a relocation here: salt-laden air corrodes exterior hardware such as gate operators and lock cylinders, the May–October rainy season brings near-daily thunderstorms, and the city sits in a high-risk hurricane zone where driving rain and blowing debris matter more than hail. If you are moving from out of state, these are the conditions your insurance quotes, inspections and flood review will be built around.
The housing stock matters just as much. Census ACS 5-year (2022) data puts the median year built at 1972, and locally the inventory is dominated by 1950s–1970s concrete block and stucco ranch homes with flat, low-slope or barrel-tile roofs, alongside a large share of two- and three-story garden apartments, condos and townhomes, plus scattered newer infill built to post-2002 Florida Building Code wind standards. Most homes are owner-occupied, according to the same Census data. A licensed real-estate professional — Premier Real Estate Group Inc or a licensed agent we refer you to — can walk you through comparing areas by commute, housing type and amenities, run video tours and remote showings while you are still out of state, and help you weigh renting first against buying first.
Relocation hazards in Oakland Park cluster around a short list: hurricane season (June 1 to November 30) and what insurers will ask for, flood zones and separate flood coverage, wind-mitigation and four-point inspections, association approval timelines for condos and townhomes, and the homestead exemption deadline after you close. Because so much of the local stock predates current wind-load and energy codes, original or lightly updated garage doors, dryer vents and ductwork are common, and roof age and condition are frequently the deciding factor in whether coverage is offered at all. Plan the insurance conversation early, not after your offer is accepted.
What to know in Oakland Park
Flood zone review before you commit
Flood zones come from FEMA flood maps, and a lender generally requires flood insurance on a home in a Special Flood Hazard Area — though homes outside one can still flood, which matters near the Middle River and its canals. Florida sellers must give buyers a flood disclosure under s. 689.302, F.S.
Four-point inspections on older homes
With a median year built of 1972, many Oakland Park homes fall into the age range where insurers commonly request a four-point inspection covering roof, electrical, plumbing and HVAC. Confirm what your carrier requires before you remove inspection contingencies.
Wind-mitigation credits
Florida insurers offer wind-mitigation credits for documented features such as roof-to-wall connections and impact-rated openings under s. 627.0629, F.S., with a licensed inspector completing the uniform mitigation form OIR-B1-1802. Credit amounts vary by insurer, so compare quotes rather than assuming a result.
Condo milestone inspections and reserve studies
Oakland Park has a large share of condos and two- and three-story buildings, so ask the association for its milestone structural inspection report where the building is three stories or taller and has reached 30 years (s. 553.899, F.S.), plus the structural integrity reserve study required under s. 718.112(2)(g), F.S.
Association approval timelines
HOA and condominium associations may require buyer or tenant approval and estoppel certificates, and association documents and budgets are part of due diligence. Locally, those rules apply mostly to condo, townhome and newer gated developments rather than the older single-family blocks.
Salt air and hardware condition
Salt-laden air from the Atlantic corrodes garage door springs, rollers and tracks, gate hardware and operators, and exterior lock cylinders, often years before comparable inland equipment fails. Build that into your inspection scope and your post-closing maintenance plan.
Homestead and residency steps
Relocating owners should plan for insurance binding before closing and for driver license, vehicle registration and voter registration steps that can support establishing Florida residency. The homestead exemption application goes to the county property appraiser, generally by March 1 of the year after moving in.
How we help
- Compare areas remotelyWe compare areas by commute, housing type and amenities so you can narrow the search before you fly in. Video tours and remote showings let you see mid-century CBS ranch homes, townhomes and condos without repeat trips.
- Rent first or buy firstWe walk through the trade-offs of renting first versus buying first, including association approval steps that apply to tenants as well as buyers. The right choice depends on your timing, financing and how settled your work situation is.
- Florida insurance basicsWe explain how four-point and wind-mitigation inspections fit into a Florida purchase and why roof age comes up so often in coastal Broward-area quotes. For market-of-last-resort questions, we point you to Citizens Property Insurance Corporation and the Florida Office of Insurance Regulation.
- Association document review supportWe help you request governing documents, budgets, approval applications, estoppel certificates and, for qualifying buildings, milestone and SIRS reports. Approval is always the association's decision, so we cannot promise an outcome.
- Closing tax orientationWe outline which Florida closing taxes may appear on your statement and point you to the free Florida Doc Stamp & Closing Tax Calculator on this site at /tools/florida-closing-costs. Who pays each item is set by the purchase contract and is negotiable.
- Homestead exemption reminderAfter closing, we remind you to apply for the homestead exemption with the county property appraiser if the home becomes your permanent residence. Save Our Homes caps assessment increases going forward, and portability applies only to a prior Florida homestead.
Florida rules and paperwork in Oakland Park
Florida brokerage is regulated by the Florida Department of Business and Professional Regulation (DBPR), Division of Real Estate, under the Florida Real Estate Commission (FREC). The paperwork for a relocation purchase or lease is the same as any Florida transaction: brokerage relationship disclosure, purchase contract or lease, seller disclosures including the residential flood disclosure, condominium or HOA governing documents and approval applications, and title and closing documents. On closing taxes, documentary stamp tax on the deed is 70 cents per 100 dollars of the price (s. 201.02, F.S.), documentary stamp tax on a new mortgage note is 35 cents per 100 dollars of the amount financed (s. 201.08, F.S.), and nonrecurring intangible tax on a new mortgage is 2 mills (0.2%) of the amount (s. 199.133, F.S.); allocation is contract-driven and negotiable. Florida has no state personal income tax, but property taxes and insurance costs vary widely by county and coastal exposure — confirm details with the county property appraiser, the Florida Department of Revenue, and a Florida attorney or CPA. A Florida license is valid statewide; out-of-state agents generally cannot perform brokerage services here without one, though referral arrangements between brokerages are common. Verify license status with DBPR.
Premier Real Estate Group Inc is a licensed Florida real estate brokerage (broker license BK3314523). Verify at Florida DBPR.
Timing and next steps
Statewide, relocation inquiries peak in winter and early spring when seasonal visitors are in state, and again in summer for households moving before the school year. In Oakland Park, activity also builds ahead of and during hurricane season — roughly May through November, peaking August through October — with a secondary bump in the fall as snowbirds return and reopen seasonal homes and condos. Insurance binding, association review and flood documentation all take time, so start earlier than you think you need to. Call (954) 703-4504 or send a request with the form on this page for a free consultation with no obligation; a licensed real-estate professional will contact you by phone or email.
Areas and nearby cities we can include in a search: Downtown Oakland Park / Culinary Arts District, Coral Heights, Lloyd Estates, North Andrews Gardens, the Oakland Park Boulevard and Dixie Highway corridors, the Middle River area, Oakland Forest, adjacent Coral Ridge and Wilton Manors, and nearby Fort Lauderdale, Pompano Beach, Lauderdale Lakes, Lauderhill, Lauderdale-by-the-Sea, Tamarac and Sunrise.
Moving to Florida in Oakland Park: common questions
- Do I need flood insurance in Oakland Park?
- It depends on the FEMA flood zone for the specific address. A lender generally requires flood insurance on a home in a Special Flood Hazard Area, and homes outside one can still flood — a real consideration near the tidal Middle River and its canals. Flood damage is generally excluded from standard homeowners policies, so separate NFIP or private coverage is the usual route.
- Why do insurers keep asking about my roof?
- With a median year built of 1972 per Census ACS 5-year (2022) data, much of the local stock is old enough that insurers commonly request a four-point inspection of roof, electrical, plumbing and HVAC. Roof age and condition are frequently the deciding factor in whether coverage is offered at all. Confirm requirements with your insurance agent before you waive contingencies.
- Should I rent first or buy first when moving here?
- Both work, and the right answer depends on your financing, timing and how much you want to see in person first. Renting can give you time to compare areas by commute, housing type and amenities, while buying avoids a second move. Note that associations may require approval for tenants as well as buyers, and we cannot predict an approval decision.
- What should I ask for if I am buying a condo?
- Ask the association for governing documents, budgets, the approval application and an estoppel certificate. For buildings three stories or taller that have reached 30 years, ask for the milestone structural inspection report under s. 553.899, F.S., and the structural integrity reserve study under s. 718.112(2)(g), F.S. Verify current status directly with the association.
- When do I apply for the homestead exemption?
- If the Oakland Park home becomes your permanent residence, you apply to the county property appraiser, generally by March 1 of the year after moving in. The exemption reduces taxable value and the Save Our Homes cap limits assessment increases going forward. Portability applies only if you had a prior Florida homestead — verify with the county property appraiser.
- How can I tell what my current home or a target home is worth?
- We offer a free comparative market analysis, which is an opinion of value prepared by a licensee — not an appraisal and not an automated estimate. Pricing depends on condition, roof and insurance profile, flood zone and association status. Call (954) 703-4504 to request one.
Tell us about your move — Oakland Park
Where you're headed, when, and whether you'll buy or rent. A licensed real-estate professional will contact you.
Licensed brokerage
Premier Real Estate Group Inc
Broker of record Maxim Bohadana, Florida broker license BK3314523
(954) 703-4504